

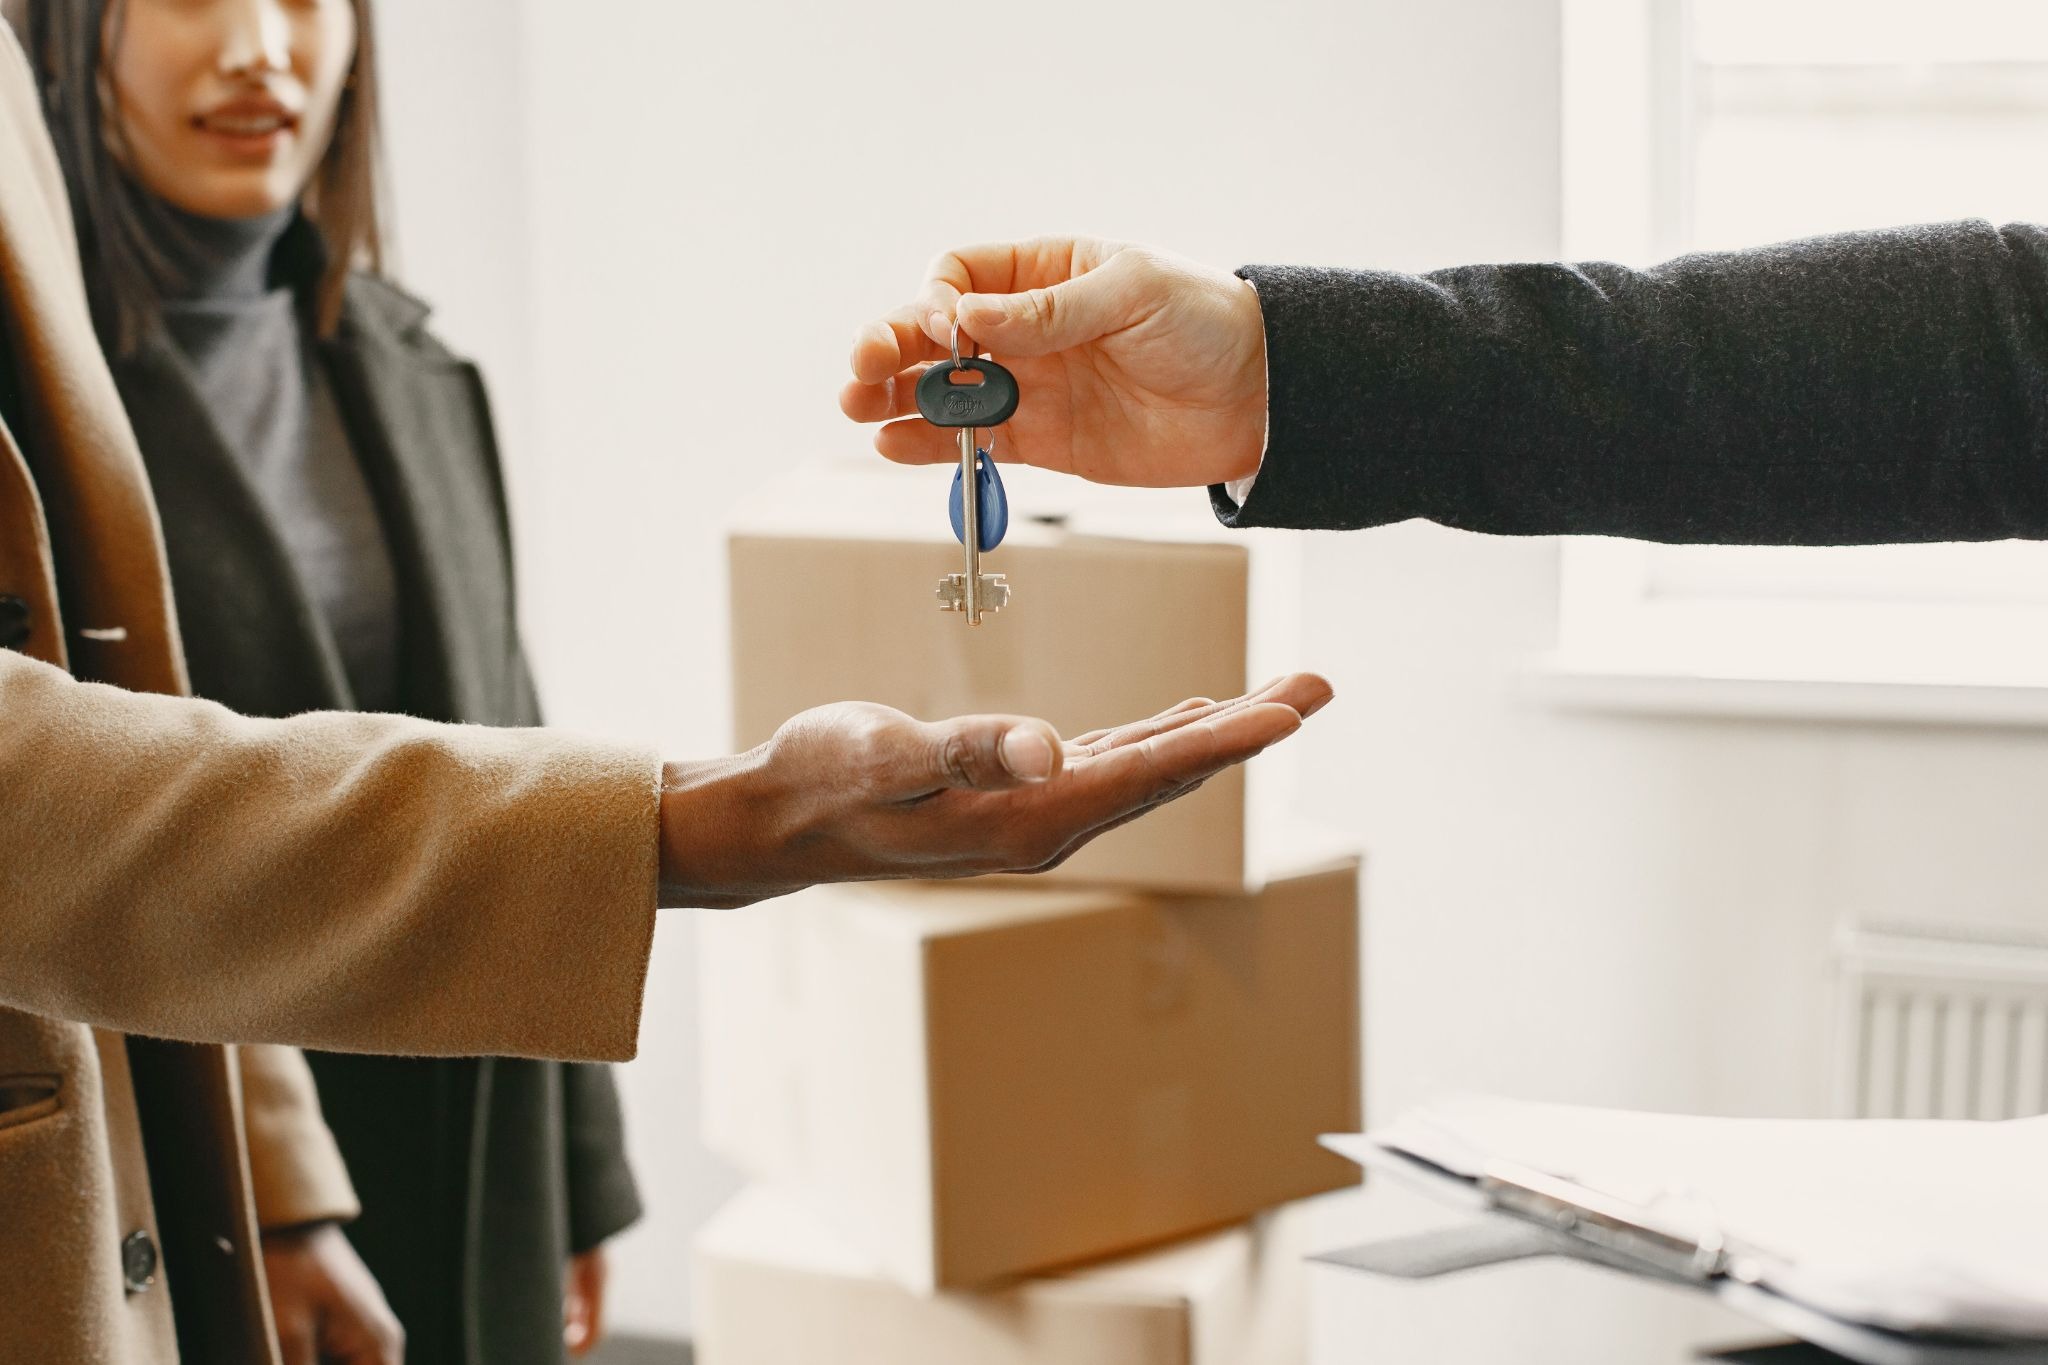
Most Georgia homeowners hear foreclosure and picture court dates, sheriff sales, and months of stress. There's a quieter path that skips most of that drama, and it's called a deed in lieu of foreclosure. In simple terms, you hand the deed of your home back to the lender, and in exchange, they agree not to take you to court over the unpaid mortgage.
This option gets overlooked because banks rarely mention it first. They'd rather collect payments or push a standard foreclosure, which is why so many owners never learn this door is open until they start asking questions on their own.
Georgia Homeowners Are Considering This Option
Job loss, medical bills, divorce, or a sudden drop in income can turn a manageable mortgage into a burden overnight. When payments fall behind by three or four months, panic sets in, and people start searching for any way out that doesn't wreck their future.
A deed in lieu often causes less damage to credit scores than a full foreclosure, and it closes the chapter faster. Instead of waiting a year or longer for a foreclosure to run its course, the whole thing can wrap up in a matter of weeks once paperwork is approved.
Some owners pair this route with selling directly to a cash buyer first, since local company Easy Sell ATL works with homeowners facing exactly this kind of pressure and can sometimes offer a faster exit before foreclosure paperwork even starts.
How the Process Works Step by Step
Getting from "behind on payments" to a signed deed in lieu involves a handful of clear stages:
Contact your loan servicer and ask directly about deed in lieu programs
Submit a hardship letter explaining why payments stopped
Provide income documents, bank statements, and tax records
Get the home appraised so the lender knows its current value
Sign the agreement once terms are approved
Move out by the agreed date and hand over keys and deed
Each lender moves at a different pace, so patience matters here. Some approvals take two weeks; others stretch past a month if the servicer is backed up with requests.
Deed in Lieu vs Short Sale vs Regular Foreclosure
Homeowners often confuse these three paths, so a side-by-side view helps clear things up:
Option | Time to Complete | Credit Impact | Who Handles the Sale |
Deed in Lieu | Weeks to a couple of months | Moderate | Lender takes the property directly |
Short Sale | Several months | Moderate to high | Homeowner lists and sells the home |
Regular Foreclosure | Several months to over a year | High | Court and sheriff sale process |
A short sale demands more effort since you're still responsible for finding a buyer and negotiating price. A deed in lieu removes that burden completely, which is why tired homeowners lean toward it when they simply want the situation closed.
Who Qualifies for This Option
Lenders won't approve everyone who applies, so check these boxes first:
The home has no second mortgage or lien attached
Payments are genuinely behind due to hardship, not neglect
You can show proof of income and expenses
The property is in reasonably good condition
You're willing to leave the home by the set date
Homes with multiple liens complicate things, since every lienholder needs to agree to release their claim before the deed can transfer cleanly.
Red Flags to Watch Before You Sign
Always get any deficiency waiver in writing. Without it, the lender could still come after you for the difference between what you owed and what the home was worth. |
Some agreements look generous on paper, yet hide a clause that lets the lender pursue you for remaining debt months later. Reading every line, or having a housing counselor review the paperwork, protects you from a nasty surprise down the road.
Tax consequences also catch people off guard. Forgiven mortgage debt can sometimes count as taxable income, so a quick conversation with a tax professional before signing saves headaches at filing time.
Closing Thoughts
If mortgage payments feel impossible to catch up on, waiting rarely improves the outcome. Reaching out to your servicer early opens more doors than ignoring calls and letters for months on end.
Georgia homeowners facing this crossroads have real choices beyond a courtroom foreclosure. Weighing a deed in lieu against a short sale or a direct cash offer, based on your own timeline and finances, puts you back in control of a situation that felt out of your hands.
Quick Answers to Common Questions
Does a deed in lieu stop foreclosure completely in Georgia?
Yes, once the lender accepts and the deed transfers, the foreclosure process ends because the debt is settled through the property itself.
Will my credit recover faster than after a foreclosure?
Generally yes. Many owners see their score rebound sooner since a deed in lieu is viewed as slightly less severe by credit models.
Can I stay in the home during the process?
Usually you remain in the home until the agreed move-out date, which the lender sets during negotiations.
Is a deed in lieu the same as walking away?
No, walking away means abandoning the home with no agreement. A deed in lieu is a formal, negotiated transfer with legal protections built in.